Tuesday, January 13, 2015

Monday, January 12, 2015
WI Real Estate & Short Sale Solution: Waukesha, Jefferson & Dodge Counties 920-988-0048: Great Duplex in Waterloo! 270 N. Monroe St.-Waterl...
WI Real Estate & Short Sale Solution: Waukesha, Jefferson & Dodge Counties 920-988-0048: Great Duplex in Waterloo! 270 N. Monroe St.-Waterl...: Amber Castonguay Phone Number Direct: 920.988.0048 Text: 920.988.0048 Toll-F...
Saturday, January 10, 2015
Making an Offer on a Short Sale? What You Need to Know......Amber Castonguay 920.988.0048
Making an Offer on a Short Sale? What You Need to Know

Are you looking to buy a new home? Are you thinking that now's a great time to find bargains? Before you make an offer, it pays to know a little about the seller's situation.
If a home is being sold for below what the current seller owes on the property—and the seller does not have other funds to make up the difference at closing—the sale is considered a short sale. Many more home owners are finding themselves in this situation due to a number of factors, including job losses, aggressive borrowing against their home in the days of easy credit, and declining home values in a slower real estate market.
A short sale is different from a foreclosure, which is when the seller's lender has taken title of the home and is selling it directly. Homeowners often try to accomplish a short sale in order to avoid foreclosure. But a short sale holds many potential pitfalls for buyers. Know the risks before you pursue a short-sale purchase.
You're a good candidate for a short-sale purchase if:
* Not all real estate practitioners are REALTORS®. A REALTOR® is a member of the NATIONAL ASSOCIATION OF REALTORS® and is bound by NAR’s strict code of ethics.
Note: This article provides general information only. Information is not provided as advice for a specific matter. Laws vary from state to state. For advice on a specific matter, consult your attorney or CPA.


A short sale is different from a foreclosure, which is when the seller's lender has taken title of the home and is selling it directly. Homeowners often try to accomplish a short sale in order to avoid foreclosure. But a short sale holds many potential pitfalls for buyers. Know the risks before you pursue a short-sale purchase.
You're a good candidate for a short-sale purchase if:
- You're very patient. Even after you come to agreement with the seller to buy a short-sale property, the seller’s lender (or lenders, if there is more than one mortgage) has to approve the sale before you can close. When there is only one mortgage, short-sale experts say lender approval typically takes about two months. If there is more than one mortgage with different lenders, it can take four months or longer for the lenders to approve the sale.
- Your financing is in order. Lenders like cash offers. But even if you can’t pay all cash for a short-sale property, it’s important to show you are well qualified and your financing is set. If you're preapproved, have a large down payment, and can close at any time, your offer will be viewed more favorably than that of a buyer whose financing is less secure.
- You don’t have any contingencies. If you have a home to sell before you can close on the purchase of the short-sale property—or you need to be in your new home by a certain time—a short sale may not be for you. Lenders like no-contingency offers and flexible closing terms.
- Experienced real estate attorney. Only about two out of five short sales are approved by lenders. But a good real estate attorney who's knowledgeable about the short-sale process will increase your chances getting an approved contract. Also, if you want any provisions or very specialized language written into the purchase contract, a real estate attorney is essential throughout the negotiation.
- A qualified real estate professional.* You may have a close friend or relative in real estate, but if that person doesn’t know anything about short sales, working with him or her may hurt your chances of a successful closing. Interview a few practitioners and ask them how many buyers they've represented in a short sale and, of those, how many have successfully closed. A qualified real estate professional will be able to show you short-sale homes, help negotiate the purchase when you find the property you want to buy, and smooth communications with the lender. (All MLSs permit, and some now require, special notations to indicate that a listing is a short sale. There also are certain phrases you can watch for, such as “lender approval required.”)
- Title officer. It’s a good idea to have a title officer do an initial title search on a short-sale property to see all the liens attached to the property. If there are multiple lien holders (e.g., second or third mortgage or lines of credit, real estate tax lien, mechanic’s lien, homeowners association lien, etc.), it's much tougher to get that short sale contract to the closing table. Any of the lien holders could put a kink in the process even after you’ve waited for months for lender approval. If you don’t know a title officer, your real estate attorney or real estate professional should be able to recommend a few.
- Potential for rejection. Lenders want to minimize their losses as much as possible. If you make an offer tremendously lower than the fair market value of the home, chances are that your offer will be rejected and you’ll have wasted months. Or the lender could make a counteroffer, which will lengthen the process.
- Bad terms. Even when a lender approves a short sale, it could require that the sellers sign a promissory note to repay the deficient amount of the loan, which may not be acceptable to some financially desperate sellers. In that case, the sellers may refuse to go through with the short sale. Lenders also can change any of the terms of the contract that you’ve already negotiated, which may not be agreeable to you.
- No repairs or repair credits. You will most likely be asked to take the property “as is.” Lenders are already taking a loss on the property and may not agree to requests for repair credits.
* Not all real estate practitioners are REALTORS®. A REALTOR® is a member of the NATIONAL ASSOCIATION OF REALTORS® and is bound by NAR’s strict code of ethics.
Note: This article provides general information only. Information is not provided as advice for a specific matter. Laws vary from state to state. For advice on a specific matter, consult your attorney or CPA.
Amber Castonguay, ABR, CDPE, E-Pro
Broker Associate
Re/Max Realty Center
Cell/Text: 920.988.0048
Fax: 866.211.2826
AmberCastonguay@gmail.com
Re/Max Realty Center
Cell/Text: 920.988.0048
Fax: 866.211.2826
AmberCastonguay@gmail.com
If you have Family, Friends or Neighbors that are struggling with their mortgage there are options! Contact Amber Castonguay, your local CDPE & SHORT SALE EXPERT to see what your options are!

Friday, December 12, 2014
Would you like to be FULLY released from your mortgage with No cost to you? Ask me how......Amber Castonguay 920.988.0048
Would you like to be FULLY released from your mortgage with No cost to you?
Over the last year many areas in our nation have been feeling a bit of a housing crunch. This housing crunch is the result of different factors depending on the particular area you are located. No matter what the factors are, an increasing amount of people have been falling behind on payments and are facing foreclosure.
In comes the short sale. Many people in and out of real estate have been talking about the real estate short sale. Every individual situation will differ slightly depending on the location of the property, and the particular lenders short sale policy.
Put simply a short sale is when a bank agrees to take less money for a property than is owed. (No they will not sell it back to the owner for this price). A home can be sold on the local real estate market as a short sale or it can be negotiated by an individual investor who will purchase the home for less.
I do not recommend using the investor because it limits the potential buyer pool and puts all of your eggs in one basket. Using a Realtor to list a short sale provides the greatest possibility that the home will not go to auction.
The first step is listing the home and giving the Realtor a letter of authorization to negotiate with the bank.
The Realtor then contacts the bank and asks for their specific short sale policy. Banks will usually require a letter of hardship, financial info (pay stubs, w2?s, bank statements), and the listing agreement. This can be forwarded by the Realtor, but some banks require the owner of the property to complete the personal info.
Once an offer is made, all of the information above is forwarded as well as the offer and a loan status report on the buyer. The loan status report shows the bank the buyers ability to pay.
Now that everything is together and in the banks possession, they will take anywhere from 24 hours to 45 days to accept the offer. Short sales require buyers to be patient. Be patient, if you want a good deal you will have to wait. If you don?t want to wait, find a regular home with a higher ?Buy it Now? price.
If the offer is accepted then the bank will usually want a closing pretty fast.
What happens to the difference? When the house is sold for less than is owed there is some money left over. The bank will forgive the debt, however, they will record the money lost is income to the seller via a 1099 form. A CPA or Tax Attorney should be consulted on how to deal with this.
What happens to your credit in a short sale? The debt is paid and the excess is forgiven. Your credit score will not go down nearly as much as a foreclosure that makes it to auction. Completing the foreclosure process is reported to reduce your credit by as much as 300 points. Contact Amber today!
Amber Castonguay, ABR, CDPE, E-Pro
Broker Associate
Re/Max Realty Center
Cell/Text: 920.988.0048
Fax: 866.211.2826
AmberCastonguay@gmail.com
Re/Max Realty Center
Cell/Text: 920.988.0048
Fax: 866.211.2826
AmberCastonguay@gmail.com
If you have Family, Friends or Neighbors that are struggling with their mortgage there are options! Contact Amber Castonguay, your local CDPE & SHORT SALE EXPERT to see what your options are!
Friday, December 5, 2014
You don't want to miss this, see where it stops! Canadian Pacific Holiday Train: Stops in Wisconsin
Canadian Pacific Holiday Train: Stops in Wisconsin
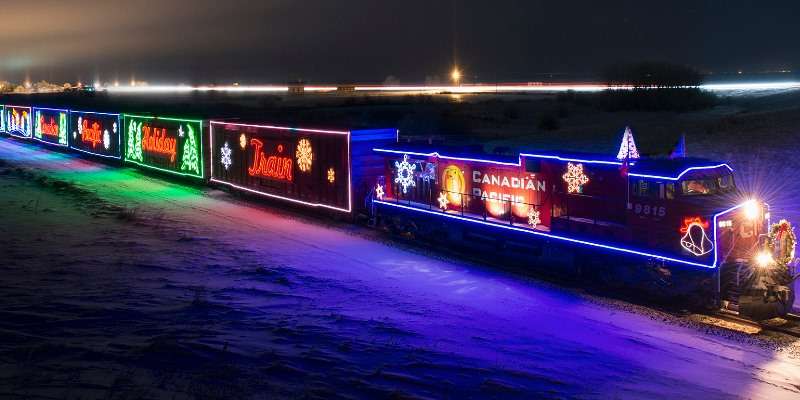
Longest Rolling Food Bank Fundraiser
The 16th annual Canadian Pacific Holiday Train will be rolling through Wisconsin this December! North America’s longest rolling food bank will make stops in 10 Wisconsin communities and feature holiday light shows with live music by Kira Isabella and Home Free. Between the music and holiday light shows, there is something for the whole family to enjoy!CP Holiday Train Schedule: Stops in Wisconsin
Sunday, December 7th
- Sturtevant - 5:20 PM
- Address: 9900 East Exploration Ct., Amtrak Depot
- Milwaukee - 6:50 PM (Show at 7:15)
- Address: 433 West St. Paul Avenue, Amtrak Depot
- Hartland - 8:45 PM
- Address: Parking lot adjacent to Cottonwood Avenue and Pawling Avenue
- Columbus - 10:30 PM (15 minute Stop N' Go)
- Address: 359 North Ludington Street, Amtrack Depot
- Portage - 1:15 PM
- Address: 400 West Oneida Street, Amtrak Station
- Wisconsin Dells - 2:45 PM
- Address: 100 La Crosse Street, Amtrak Depot
- Mauston - 4:15 PM
- Address: Division Street railway crossing
- Tomah - 5:30 PM
- Address: 205 North Superior Avenue, Amtrak Depot
- Sparta - 6:40 PM
- Address: Corner of South Water Street and Milwaukee Street
- LaCrosse - 9:00 PM
- Address: 601 Saint Andrew Street
This entry was posted in Tours, Holiday Events
Behind on your mortgage? I can help........Amber Castonguay 920.988.0048
Behind on your mortgage? I can help........Amber Castonguay 920.988.0048

Over the last year many areas in our nation have been feeling a bit of a housing crunch. This housing crunch is the result of different factors depending on the particular area you are located. No matter what the factors are, an increasing amount of people have been falling behind on payments and are facing foreclosure.
In comes the short sale. Many people in and out of real estate have been talking about the real estate short sale. Every individual situation will differ slightly depending on the location of the property, and the particular lenders short sale policy.
Put simply a short sale is when a bank agrees to take less money for a property than is owed. (No they will not sell it back to the owner for this price). A home can be sold on the local real estate market as a short sale or it can be negotiated by an individual investor who will purchase the home for less.
I do not recommend using the investor because it limits the potential buyer pool and puts all of your eggs in one basket. Using a Realtor to list a short sale provides the greatest possibility that the home will not go to auction.
The first step is listing the home and giving the Realtor a letter of authorization to negotiate with the bank.
The Realtor then contacts the bank and asks for their specific short sale policy. Banks will usually require a letter of hardship, financial info (pay stubs, w2?s, bank statements), and the listing agreement. This can be forwarded by the Realtor, but some banks require the owner of the property to complete the personal info.
Once an offer is made, all of the information above is forwarded as well as the offer and a loan status report on the buyer. The loan status report shows the bank the buyers ability to pay.
Now that everything is together and in the banks possession, they will take anywhere from 24 hours to 45 days to accept the offer. Short sales require buyers to be patient. Be patient, if you want a good deal you will have to wait. If you don?t want to wait, find a regular home with a higher ?Buy it Now? price.
If the offer is accepted then the bank will usually want a closing pretty fast.What happens to the difference? When the house is sold for less than is owed there is some money left over. The bank will forgive the debt, however, they will record the money lost is income to the seller via a 1099 form. A CPA or Tax Attorney should be consulted on how to deal with this.
What happens to your credit in a short sale? The debt is paid and the excess is forgiven. Your credit score will not go down nearly as much as a foreclosure that makes it to auction. Completing the foreclosure process is reported to reduce your credit by as much as 300 points. Contact Amber today!
Subscribe to:
Posts (Atom)